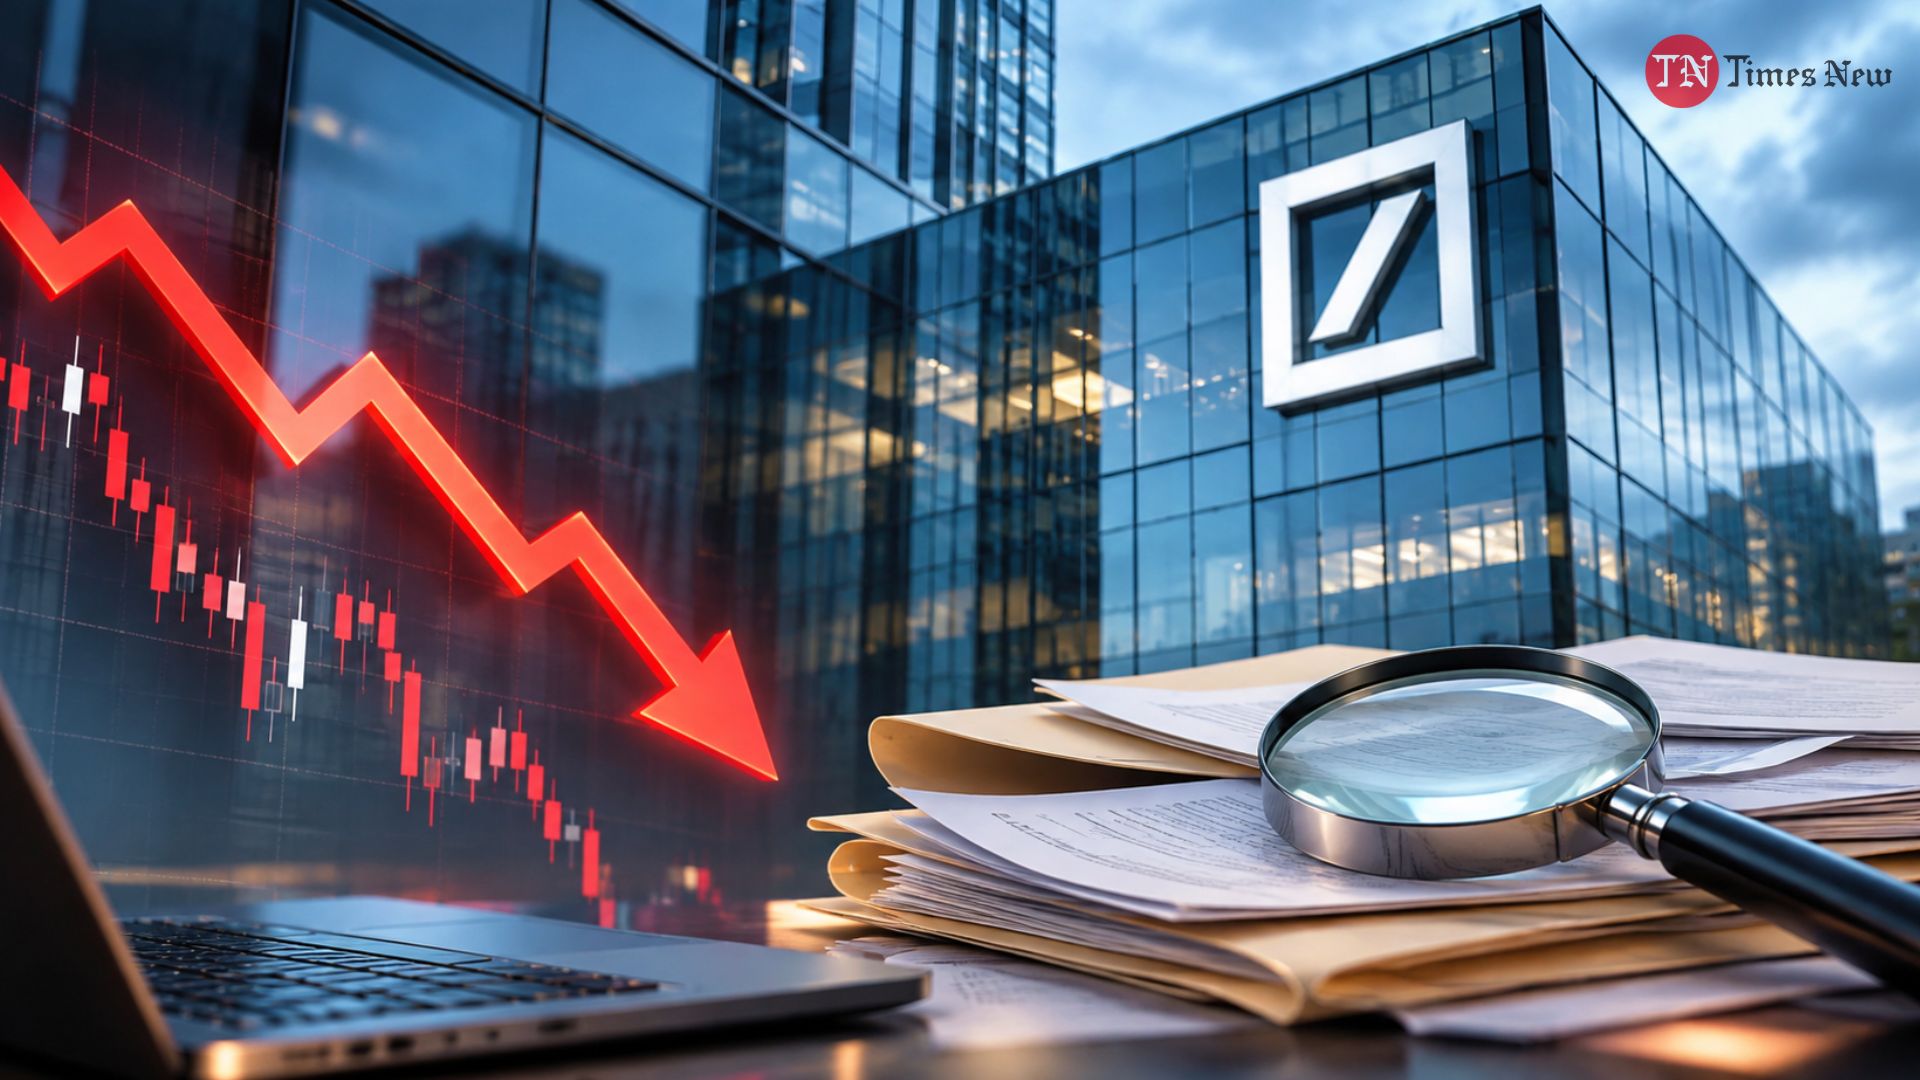
Deutsche Bank shares fell 5.2% in early trading on Tuesday after the German lender responded to media reports based on leaked documents detailing its past dealings with high-profile clients, including Russian oligarchs, US President Donald Trump and late financier Jeffrey Epstein. The reports, published by a consortium of international journalists in outlets such as Der Spiegel, The Financial Times and The New York Times, raised questions about the bank’s historical client relationships and business practices.
In a statement, Deutsche Bank said the incidents highlighted in the reports dated back many years, in some cases nearly two decades, and stressed that it had significantly strengthened its internal controls since then. The reports were based on approximately 15 million leaked records, including emails and meeting minutes, obtained by two journalists and examined by a consortium of more than 200 journalists. Reuters said it had not immediately verified the claims.
The bank, which has spent years rebuilding its reputation following regulatory penalties linked to anti-money laundering controls and other compliance failures, said it was a different institution today. Under CEO Christian Sewing, who took charge in 2018, Deutsche Bank has returned to profitability and recorded strong financial results, including record profits in 2025. The lender added that, given the legacy nature of the matters, any potential financial impact was not expected to be significant.
Pic Courtesy: google/images are subject to copyright
You May Also Like
CVC Plans to Withdraw from €3 Billion IRCA Acquisition Deal
17 November 2026
California Sues OpenAI Over AI-Driven Cyberattacks
17 November 2026